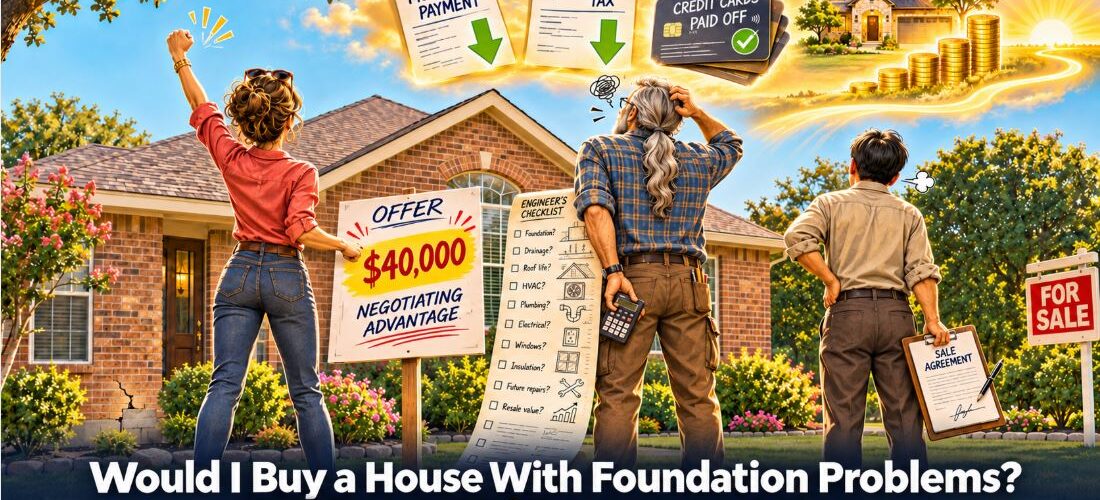
Would I Buy a House With Foundation Problems? Hell Yes! Here’s Why.
November 4, 2026
by Elena Garrett, Realtor | Nov 2026
For some homebuyers, the words foundation problems mean the end of a possibility. For me, they can mean the beginning of one. A financial possibility, to be precise.
I love finding an advantage where other people don’t see one. And sometimes, the very thing that scares other buyers away can become your greatest negotiating opportunity. In fact, one of the best financial decisions my husband and I ever made was purchasing a house that other buyers were afraid to buy.
And the financial benefits of that decision continued throughout the 20 years we lived there. Let me tell you what happened.
The house nobody wanted
Years ago, my husband and I were shopping for a home. We found a house in a subdivision with several other homes for sale. It wasn’t particularly impressive. In fact, it was pretty pathetic looking during our first walkthrough. It needed painting, had outdated countertops, and hadn’t received many upgrades. But honestly, most houses in that subdivision looked pretty similar.
There was one major difference. Our house had foundation problems, and the seller didn’t want to fix them. So he was selling as-is. Other buyers were walking away.
The house had a surprising feature I did not even know I wanted: it had a fish pond. For some reason, that fish pond stole my heart the moment I saw it, and the ugly house the fish pond belonged to was a headscratcher for me to consider. But I knew the moment I saw the fish pond that it was MY house.
My husband was pretty displeased when I suggested we buy THAT home. “Why”, he asked, “would we want to mess with a home with foundation issues when other homes were available? Honey, let’s buy an updated home, and I can install the fishpond there for you for less than the foundation will cost us!” But, no, it might be my Russian stubbornness or some strange intuition, or both, but I had a persistent and very intense feeling that there was some invisible value there that I could sense, even though I could not fully articulate. My husband could not understand my logic. But while him and other buyers were seeing a problem, I was seeing a strange flicker or some great opportunity.
Eventually, my husband and I came to an agreement. If we could negotiate a big enough discount on the fish pond house, my husband would reluctantly sign off on the purchase docs. I swore up and down to my husband that I would be delighted to take on dealing with quotes, negotiations, repairs, and cosmetic updates myself, without create a huge honey-do list for him. Finally, he gave me a go-ahead to start the price negotiation on the fish pond house.
Lesson 1: My husband saw a problem. I saw a calculation.
My husband was an engineer. He loved looking at technical side of all things. So was my father. And if there’s one thing I’ve learned from living with engineers for years, it’s that they rarely go on a gut feeling, like I often did, and it took them much longer to make a decision that looked pretty straightforward from my point of view.
When I finally got my husband’s buy-in on negotiating on the house, my husband bought a separate notebook to keep track of his worries of things that might go wrong with my plan. Unlike me, he actually HAD repaired the foundation of a previous home, and that project had cost him approximately $11,000, not counting the additional repairs. In his estimate, we were looking at a minimum of $20,000 or more to get the foundation and the collateral issues fixed.
In addition, he began considering everything that might go wrong. How would the foundation be repaired? Which types of piers would work in this soil? Would the bricks crack even more? What about windows? What would happen if this needed fixing? What about that? His list of concerns was several pages long.
Meanwhile, my calculation was much simpler.
How much could we negotiate? How much might the repairs cost? How much margin did I need to feel the risk was worth it? That’s what I needed to know.
The seller had originally listed the house for somewhere around $160,000–$170,000, as I recall. After several price reductions, the asking price was approximately $134,000. I made a deal with my husband that if I could take his $20,000 repair estimate and negotiate at least 30K or more in price reduction, he would sign on the purchase agreement.
And guess what? The seller was so sick of buyers walking away from him home, and having to maintain the fishpond, that with relatively low effort we negotiated it down to $94,000. That’s approximately $40,000 below the seller’s already-reduced asking price. Now we had something interesting to work with.
What if everything went wrong?
At the time, I estimated that the foundation work itself would probably cost somewhere around $11,000-$20,000. I also understood that we’d likely need to repair some sheetrock, repaint, and possibly fix other cosmetic damage. Fine. I wasn’t particularly intimidated by that.
As a little girl growing up in Russia, growing up in a very poor family, I had helped my father build our family dacha. We had no funds for building the house, so my Dad became a very creative first-time home builder. He started to build the house from scrap pieces of wood, metal, and plastics he would find that other large construction projects discarded, and he would collect and bring to our dacha (a free lot of land the government allotted our family as a part of his work retirement program or something of that nature).
I helped my Dad to measure the foundation space before it was dug, I held a bucket of raw cement for him while the brick walls were being built, and I helped to hold the glass while the windows being installed. I helped to design the kitchen space, the staircase, and the vegetable racks in the basement, I knew that a pretty elaborate and well-made structure could be made from spit, wood scraps, some some glue and duct tape. My Dad and I started many designs, dismantled or altered them if they did not work out, found additional materials, and always found a way to turn other people’s trash into a decent looking house (that is still standing to this day, I might add!).
So my question wasn’t whether something might go wrong. I knew things would certainly go wrong at least a few times, as most things do, before the foundation project was finished. My question was whether we had negotiated enough financial room to deal with it if it did. And in my mind, we had.
And what if it did go all wrong?
Let me be honest about something, though. At that time, I hadn’t considered the possibility that foundation movement might have damaged the underground plumbing. Because in Russia, utilities were never done undergrounds, the idea of the pipes being inside of the foundation was not yet in my mind. Today, I would certainly include that in my evaluation.
But here’s what’s interesting. Looking back, even if we had needed to replace the plumbing throughout the entire house, and even if the additional repairs had consumed our entire $40,000 negotiating advantage, the deal could still have been financially acceptable. We might have broken even on the immediate price advantage. We might even have come out slightly behind. But we wouldn’t necessarily have lost the other advantages of owning a home purchased at a much lower price. And that’s the distinction that mattered to me.
I didn’t need a guarantee that nothing would go wrong (my previous construction experience was filled with things that went wrong). I needed to know that I could live with the financial consequences if it did.
In my judgment at the time, the probability of ending up with a totally disappointing financial outcome was relatively small. I mentally estimated it at something like 10%. I gave it a 40%-50% chance of getting everything well within our budget and still having money for additional upgrades. And I believed there was roughly a 30% chance that we’d come out very much ahead on the entire deal.
Those weren’t scientific probabilities. They were my own assessment of the situation, based on what I understood about the house and the money involved. To me, it looked like a very attractive opportunity. A relatively small chance of losing a little, compared with a much larger chance of gaining substantially.
So… How Did My Bet Play Out? What did the foundation actually cost us?
Here’s where the story gets even better. After purchasing the house, we had the foundation repaired.
The actual foundation repair cost approximately $4,900. We spent about another $1,100 repairing the sheetrock. That’s approximately $6,000 altogether.
Remember, we had negotiated the purchase approximately $40,000 below the seller’s last asking price. We had secured a $40,000 price reduction and spent only about $6,000 addressing the problem.
But that wasn’t the end of our financial benefits. It was only the beginning!
The advantage that kept paying us every month
Because we purchased the house at such a favorable price, we started with a much smaller mortgage than we might otherwise have needed. Our original mortgage interest rate was approximately 5.6%.
At that rate, borrowing $40,000 less on a 30-year mortgage translates into approximately $230 less in principal and interest every month. That’s nearly $2,800 a year in additional cash-flow flexibility. And the benefit doesn’t stop after the first year. It continues month after month.
Over a hypothetical 20-year period, that difference in mortgage payments adds up to approximately $55,000 in lower housing expenses, assuming the original loan terms continued.
Of course, our actual financing changed over the years as we refinanced. But the original purchase price gave us a tremendous head start. At one point, while other homeowners I knew were paying approximately $1,500–$1,700 per month for their mortgages on their fully remodeled, pretty homes, we were paying around $600 for our fixer upper that we were slowly improving as time went on.
We were living in the same subdivision. But our financial obligations were dramatically different. And that gave us choices.
Then we discovered another advantage: Property taxes.
Here’s something I hadn’t even considered when we were negotiating the house. Our lower purchase price was reflected in a lower property valuation after we purchased it. As a result, our property taxes went down automatically the 2nd year we were in the house.
We were actually surprised to see our monthly housing payments decrease the following year because of the county’s reassessment. So now we were benefiting from both a lower mortgage and lower property taxes.
But my husband got an idea. Remember that engineer who had been so worried about buying the house? Well, he was also considerably more financially savvy about home ownership in Texas than I was at that point. A year or two later, he introduced me to something I hadn’t even known existed.
A property tax protest. He documented the imperfections in our house, including the foundation issues, and successfully challenged its appraised value. Our taxes went down – again, freeing up even more more cashflow for us each month. And in our case, that lower valuation continued benefiting us for years afterward.
Even after the foundation had been repaired, our taxable value remained substantially lower than that of many comparable homes in the neighborhood.
We had negotiated a lower purchase price. We had a lower mortgage. And now we had another long-term financial advantage through our property taxes.
And then came opportunities I couldn’t have predicted.
Over the years, that lower housing expense gave us financial flexibility. At one point, we refinanced the house and used some of the proceeds to pay off several high-interest credit cards. I couldn’t begin to calculate the full financial benefit of that decision. But it helped us to get through some tough periods with less stress.
At other times, we were able to access equity and invest in additional real estate. Those investments created opportunities of their own.
Would we have managed without them? Probably. But I’m certainly glad we didn’t have to find out.
The house that other buyers were afraid to purchase became a financial tool that helped us accomplish things we might otherwise have struggled to do.
Let’s look at the numbers.
Here’s a simplified picture of what that original foundation problem meant to us financially.
| Cost or financial advantage | Amount |
|---|---|
| Cost of addressing the problem | |
| Foundation repair | $4,900 |
| Sheetrock repairs | $1,100 |
| Total actual repair cost | $6,000 |
| Original negotiating advantage | |
| Purchase price below seller’s last asking price | ~$40,000 |
| Price advantage remaining after those repairs | ~$34,000 |
| Long-term financial effects | |
| Illustrative reduction in monthly mortgage principal and interest | ~$230/month |
| Illustrative difference in mortgage payments over 20 years | ~$55,000 |
| Lower property taxes after purchase | Additional savings |
| Further property-tax reduction after protest | Additional savings |
| Refinancing to address high-interest credit-card debt | Additional financial benefit |
| Ability to access equity for other investments | Additional opportunities |
The numbers are impressive. But what interests me even more is how many of these benefits I hadn’t anticipated when we decided to buy. I knew we were getting a favorable purchase price. I knew that could mean a lower mortgage payment. I believed the repair costs were manageable, even allowing for unpleasant surprises. That was enough information for me to make the decision.
I didn’t know about the future property-tax savings. I didn’t know we would eventually refinance to address high-interest debts. I didn’t know about all the investment opportunities that would follow. Those were additional benefits we discovered along the way. And that’s perhaps the most important part of this story.
I didn’t have to predict every financial advantage to recognize that the opportunity was worth pursuing.
And remember my husband? This is what he thinks now…
The man who was filling out pages of his concerns about the foundation project when I first suggested buying this house? My very own Chicken Little?
Well, in his true fashion, he was still thinking through potential complications long after I had decided that the financial opportunity was worth accepting. But over the next 20 years, we got to see how that decision actually worked out.
And eventually, even my husband agreed. Buying that house was probably one of the best financial decisions we ever made together.
So, would I buy another house with foundation problems?
HELL YES!
As long as I understand what I’m buying, can evaluate the costs, and the financial advantages make sense.
When I am looking at a house (or any other project, for that matter), I’m not equating problems with problems. I’m equating problems with potential opportunities. And sometimes the very problem that makes other buyers walk away is what makes an opportunity possible.
The next time you see a home with a foundation repair history, don’t automatically cross it off your list. Ask yourself a different question: What financial advantage might be waiting here because other buyers are afraid to take a closer look?
You might decide the house isn’t for you. Or you might discover an opportunity that benefits your family for decades. I certainly did. And 20 years later, so did my husband.
Coming Next: Should YOU Buy a House With Foundation Issues?
Now, that’s a very different question from “Would I buy a house with foundation issues?”
You’ve heard my story. You know what I did, why I did it, and how that decision benefited my family for the next 20 years. But does that mean you should do the same? Possibly! And that’s exactly what we’ll explore in my next article.
Today, I have something I didn’t have when my husband and I purchased our home: years of experience as a Realtor helping buyers successfully purchase homes with foundation issues or previous foundation repairs. I’ve seen these situations from both sides—as a homeowner who took the opportunity and as a real estate professional helping others evaluate similar opportunities.
In the next article, “Should You Buy a House With Foundation Issues?”, I’ll share practical advice on:
- What to look for when touring a house with foundation concerns.
- How to find out what has already been repaired and what might still need attention.
- How to understand the potential costs without becoming a foundation expert yourself.
- How to determine whether the financial opportunity is worth pursuing.
My goal isn’t to convince you to buy a house with foundation problems. It’s to help you recognize when a problem might actually be an opportunity—and give you the confidence to make that decision for yourself.
Before you cross another house off your list because of its foundation, let’s take a closer look at what you might be passing up.
Coming next: Should You Buy a House With Foundation Issues? A Practical Guide for Texas Homebuyers.
72sold advertising opportunities artículos en español blog buy4cash buyers Canadian citizens cash offers creative financing dfw housing market update events financial fitness for buyers for homeowners for investors for renters for sellers holidays home purchase contracts and forms houses industry news international home buyers itin knowledge articles legal and financial market updates monthly updates mortgage moving to Texas North Texas homes owner financed houses RECA educational center rent-to-own seller financed houses selling as-is special program stats stats and trends taxes tips and tricks vendor resources videos videos for home buyers videos for investors videos for sellers