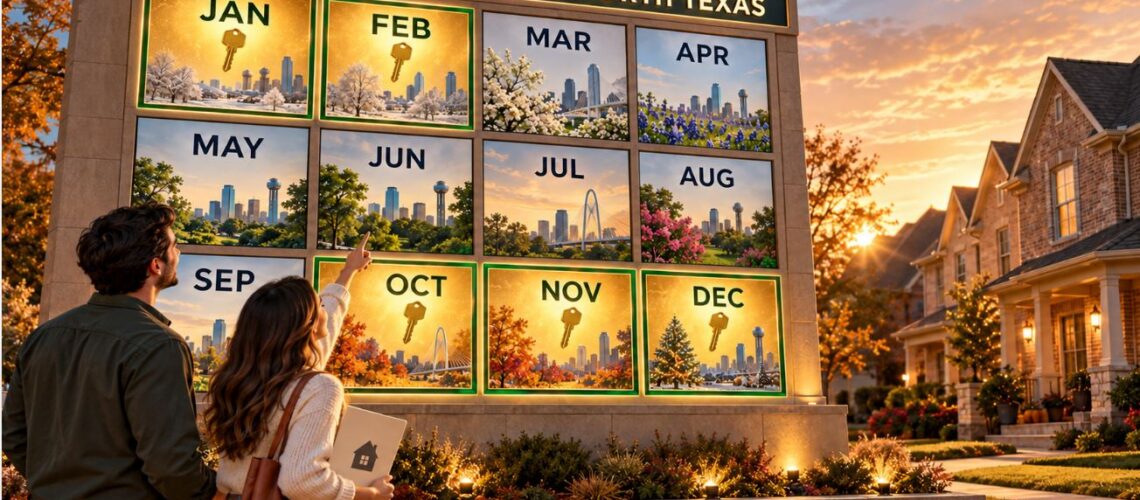
DFW Rent-to-Own: The Secret October–February Opportunity! 🏡
October 30, 2026
What fresh cranberries can teach homebuyers about the timing of seller financing and rent-to-own opportunities in Dallas–Fort Worth
By Elena Garrett | DFW Real Estate | October 2026
What do cranberries have to do with rent-to-own and seller financing? More than you think!
In fact, a simple trip to the grocery store can explain one of the most overlooked aspects of buying a home with creative financing: sometimes the opportunity isn’t just about finding the right property. It’s about looking for those opportunities at the right time of the year.
If you’ve spent months searching for rent-to-own or seller-financed homes in Dallas–Fort Worth without finding much in your price range, stay with me. You may have been shopping in the wrong season.
First, let’s go cranberry shopping
Imagine it’s the middle of May. I send you to the grocery store with one assignment: find a bag of fresh cranberries.
Can you do it? Possibly. You might discover a specialty supplier or an unusual source. But you may have to search quite a bit harder than you expected. Most grocery stores are not overflowing with fresh cranberries in May.
Now move the calendar to the middle of November.
Walk through the same grocery store. Suddenly, the fresh cranberries are right there, ready for Thanksgiving and holiday cooking. You don’t need a special strategy to find them. They’re in season.
Why such a dramatic difference? The fruit hasn’t changed. The season has. Fresh cranberries are generally harvested in the fall and sold during the fall and early winter, while frozen and dried versions are more widely available year-round.
And that brings me to the real estate connection.
Creative financing can have a season, too—but not in the way you might think
I’m not saying that hundreds of houses suddenly sprout “RENT-TO-OWN” signs every November. The more interesting opportunity is often not advertised at all. It comes from a change in a homeowner’s willingness to consider a different type of sale.
The same homeowner who dismisses seller financing in May may be willing to have a serious conversation about it in November. Not because the property has changed. Not necessarily because your offer has changed. Because the seller’s expectations have changed.
Let’s look at what happens during those months.
May: Sellers are still shopping for possibilities
Imagine approaching a homeowner in May and asking: “Would you consider seller financing—or perhaps a rent-to-own arrangement?” The owner may respond with an immediate no. Why? Because they are looking at the spring and summer selling season with enormous expectations.
They may be thinking:
- “The busiest months are still ahead of us.”
- “More buyers will come through.”
- “Perhaps we’ll get our full asking price.”
- “Why should I commit to an unconventional arrangement when a traditional buyer might appear next week?”
And from their perspective, that reasoning can feel perfectly sensible. They have not yet seen what the season will—or won’t—deliver.
Some sellers may be overestimating buyer demand or the price their property can command. But here’s something I’ve learned in real estate: you can’t easily argue people out of their expectations. They want to find out for themselves. Until then, creative financing may feel to them like giving up a promising opportunity they haven’t fully explored.
For a buyer looking for flexible terms, finding a receptive homeowner in May can feel a lot like hunting for fresh cranberries at that time of year. You might find one, but the search can be frustrating.
October: The season of expectations becomes the season of results
Now fast-forward to late October. Spring came and went. Summer came and went. The homeowner held open houses, maintained the property, perhaps reduced the price—and the house still hasn’t sold. This seller no longer has to imagine what the spring and summer market might do. They have their own results to examine.
Meanwhile, the expenses haven’t stopped. Depending on the property, they may still be paying:
- Mortgage payments
- Property taxes and insurance
- Utilities and lawn care
- Repairs, upkeep, and security for a vacant home
- HOA dues and other ownership expenses
For an owner carrying an empty house, every additional month has a real cost. And even an occupied home can be a financial or logistical burden when the owner has already moved on or needs the sale proceeds for another purpose.
Now the holidays are approaching. Instead of counting on the strongest part of the selling season still being ahead, the seller may be wondering whether they’ll carry the house into the next year.
This is when the conversation can change.
Earlier in the year, the question was: “How much might I get if I wait?” Now it may be: “What else can we do to get this property sold?.” That’s a different problem—and it invites a different set of solutions.
The exact same seller may hear a different offer
Picture two conversations about the same house.
In May: A buyer asks whether the seller would consider carrying financing. The seller says, “No, thank you. We’re expecting a normal sale.”
In November: The house remains unsold. The buyer—or another qualified buyer—asks whether a structured seller-financing proposal might help the owner move forward. This time, the seller says, “What would the terms look like?”
That’s not a guaranteed yes. But it is the beginning of a negotiation that might never have happened six months earlier. The opportunity didn’t necessarily appear because a new house came on the market. It appeared because an existing seller became more open to a different solution.
Why October through February deserves a place on your calendar
Real estate activity has a seasonal rhythm. The National Association of Realtors notes that existing-home sales generally increase in spring and summer and tend to slow in winter. The Texas Real Estate Research Center’s October 2026 housing report also describes the typical cooling in activity as the market moves past the peak summer months, while emphasizing that conditions vary by location.
That does not mean research has established that more seller-financed homes become available on a particular date. My point is more practical: for some long-unsold properties, the fall and winter months create a period when the owner is especially willing to reassess the original sales plan.
I think of October through February as a window for creative conversations, not as a magic calendar guarantee.
By March and April, some sellers begin anticipating spring buyers again. The old expectation returns: “Maybe we’ll do better if we just wait a little longer.” A seller who entertained alternatives in January may be less interested in those same terms once spring optimism returns.
If you’re a buyer who needs flexible financing, that’s a reason to search actively now rather than postponing your efforts until the traditionally busy season.
Don’t search only for homes advertised as “rent-to-own”
Here’s a mistake I see buyers make: they search listings for the magic words “rent-to-own” or “seller financing”, find very few results, and conclude that there are no opportunities. But an advertised offer is only one kind of opportunity. Another is a home whose owner might consider a well-presented proposal, even though they never advertised alternative terms.
That doesn’t mean you should assume every stale listing is desperate or financially capable of financing a sale. Many owners have existing loans, financial obligations, or other limitations that make particular structures impractical. Some simply do not want the ongoing responsibility.
The idea is to identify a seller’s actual problem and see whether your proposed terms could solve it.
For example, a thoughtful offer may address the owner’s need for a meaningful down payment, dependable monthly income, a workable timeline, or relief from the uncertainty of another prolonged listing period. In some circumstances, traditional financing or a straightforward price negotiation will still be the better answer.
Rent-to-own and seller financing are not the same thing
These terms are often mentioned together, but buyers should understand the difference.
Seller financing generally means the seller provides financing as part of the purchase rather than the buyer obtaining all purchase funds from a conventional mortgage lender. The transaction’s legal structure, down payment, interest, payment schedule, maturity or balloon provisions, and security for the debt all matter.
These arrangements are not shortcuts around financial readiness or sound contracts. In Texas, the Texas Real Estate Commission provides a Seller Financing Addendum, but other arrangements—including contracts for deed—can require different documents and careful legal review. The Consumer Financial Protection Bureau also warns that some alternative-financing structures carry risks that differ from a standard mortgage.
Before committing, buyers and sellers should have the terms reviewed by appropriately qualified professionals, including a Texas real estate attorney when needed.
How to take advantage of the seasonal opportunity
If you’re searching in Dallas, Collin, Denton, Tarrant, Rockwall, or another part of North Texas, here’s how I’d approach the coming months:
- Decide if moving to another home (via rent-to-own or seller financed purchase) is something you actually want
- Get specific about what you can afford. Read my article on that topic.
- Look beyond advertised creative-financing listings. Some homes that have been on the market for a while may be worth a respectful inquiry, even if the listing doesn’t mention alternative terms.
- Ask what matters to the seller. Is the priority a quick closing, reliable income, reduced carrying costs, or simply a clean end to a difficult listing? Structure matters more when it solves a real problem.
- Bring a credible proposal. A serious buyer with documentation and understandable terms is easier to consider than a vague request to “do rent-to-own.”
- Compare the entire deal, not just the monthly payment. Price, deposits, fees, interest, repairs, default provisions, deadlines, and the eventual path to ownership determine whether an offer is genuinely good for you.
Creative financing can expand the conversation. It doesn’t automatically make a house cheaper, safer, or easier to buy.
The best-kept secret isn’t a house. It’s timing.
If you’ve been discouraged by the limited number of rent-to-own and seller-financing listings in your price range, don’t assume the search is hopeless.
Sometimes the key isn’t finding a different house. It’s approaching the right seller at a time when they’re ready to discuss a different solution.
And if you’ve spent all spring and summer searching without success, perhaps you’ve been doing the real estate equivalent of looking for fresh cranberries in May.
Well, cranberry season is here.
For some DFW sellers, so is the season for a new conversation.
If you’re looking for rent-to-own or seller-financing opportunities in North Texas, let’s explore the possibilities—before spring changes the conversation again.
Elena Garrett works with buyers and sellers across the Dallas–Fort Worth area, including buyers interested in nontraditional purchase structures. Every property’s circumstances and every financing proposal require individual evaluation.